A used vehicle budget should cover more than the purchase price. Overseas buyers need to account for vehicle condition, export documentation, customs valuation, import duties and destination charges before agreeing to a transaction. For buyers comparing used cars for 15k, the final landed cost is a more useful measure than the advertised vehicle price.
Establish the Vehicle’s Actual Value Before Purchase
The first step is to establish whether the quoted price reflects the vehicle’s condition. Mileage is a useful starting point, but it should not be treated as proof of mechanical quality. Request the odometer reading, available service records and maintenance invoices. Compare recorded mileage across service documents and inspection photographs. Inconsistent readings need an explanation before payment.

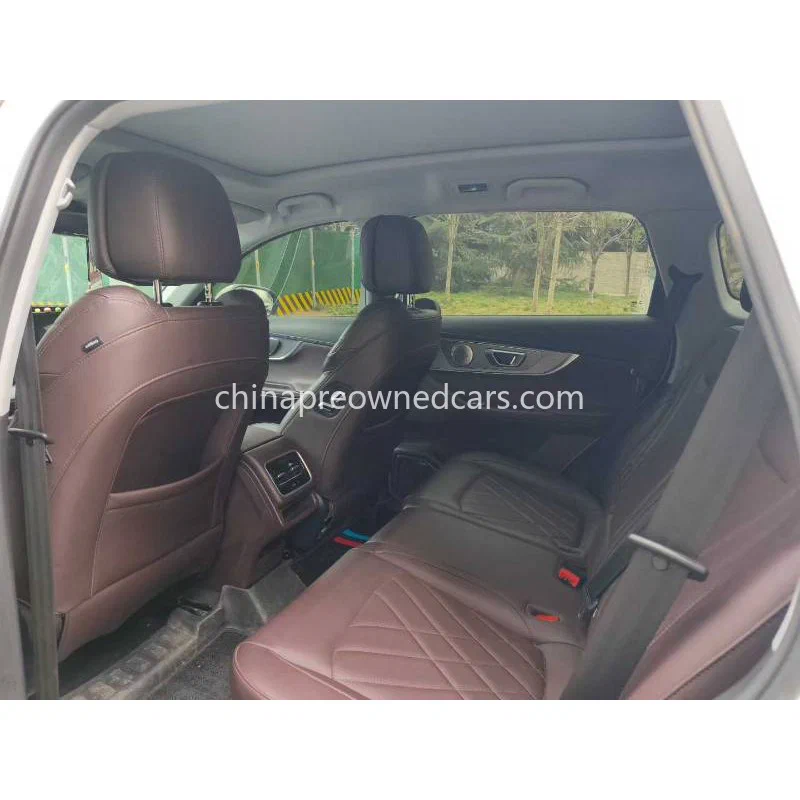
Accident history also deserves attention. Ask for photographs of the exterior, underbody, engine compartment and interior. The inspection should cover structural repairs, paint differences, chassis damage, suspension components and signs of water ingress. A vehicle condition grade is useful only when the exporter explains the grading criteria and provides supporting evidence. VIN verification should confirm that the identification number on the vehicle matches the registration and export documents. Buyers should also check whether the vehicle’s recorded history reveals ownership changes or previous damage.
For electric and hybrid models, additional checks apply. A BYD Atto 3 requires a battery state-of-health assessment, including available diagnostic information about battery capacity and fault codes. Hybrid vehicles also need checks of the battery system, engine and interaction between the two powertrains. Buyers should request the inspection date and supporting test results rather than relying on a general statement that the battery is in good condition. Charging compatibility and access to suitable servicing in the destination country should also influence the purchase decision.
Customs Valuation and Import Documentation
Customs duty can substantially change the cost of an imported vehicle. In many markets, customs authorities calculate the taxable value using a CIF basis: cost of the vehicle, insurance and freight to the destination port. The applicable duty and other taxes depend on local legislation and vehicle classification. Age-related penalties or additional charges may also apply in some markets. These rules are not uniform, and buyers should obtain a current calculation from a qualified clearing agent before confirming their budget.
Nigeria requires particular attention to its import documentation process. Form M and the Pre-Arrival Assessment Report (PAAR) are important parts of the applicable import procedure. Buyers should coordinate with their Nigerian bank and clearing agent to confirm the required documentation and processing sequence before shipment. A certificate of origin may also be required to establish where the vehicle was manufactured. Its availability and acceptable format should be confirmed against current customs requirements.
Other destination markets, including Ghana, Kenya, Uganda and Tanzania, have their own customs procedures. Vehicle age restrictions, emission requirements, left-hand-drive acceptance and roadworthiness rules can affect eligibility. Most vehicles sourced from China’s domestic market are left-hand drive. This is an important consideration for buyers because destination regulations may restrict their import or registration. Buyers should verify the current rules with local authorities or a licensed clearing agent rather than relying on outdated online guidance.
The export documentation package should be reviewed before the vehicle leaves China. Relevant records include the commercial invoice, sales contract, packing list where applicable, bill of lading, certificate of origin and export customs declaration. The exporter must also hold the appropriate export license and arrange the required pre-shipment inspection. Buyers should request copies or confirmation of these documents and establish who is responsible for obtaining each item. Missing paperwork can delay customs processing even when the vehicle itself meets import requirements.
Landed Cost, Exporter Credibility and Payment Risks
A customs valuation dispute can arise when the declared vehicle value differs from the amount accepted by destination customs authorities. Authorities may request additional evidence, compare the declaration with reference values or reassess the taxable amount. An undervalued invoice is not a reliable way to reduce import costs. It can create penalties, additional inspections and clearance delays. Buyers should retain the sales contract, payment evidence and supporting vehicle valuation information so the transaction can be explained if customs requests clarification.
The clearing agent plays a central role in preventing these problems. Before shipment, the agent should review the vehicle details, import eligibility, valuation basis and documentation. The buyer should obtain a written estimate separating customs duty, taxes, port charges, inspection fees and agent service charges. This makes it easier to identify which costs are fixed, which depend on customs assessment and which may arise from delays. Storage and demurrage charges can increase when documents are incomplete or clearance arrangements begin too late.
Exporter credibility requires similar scrutiny. A legitimate supplier should be able to explain its sourcing process, provide recent vehicle photographs, arrange independent inspection where requested and identify the legal entity receiving payment. Buyers should verify company registration and export credentials, check that the bank beneficiary matches the contracting business and request a written agreement covering vehicle specifications, condition disclosures, shipping responsibilities and refund arrangements. Payment terms should be documented. Deposits followed by balance payment against agreed inspection and shipping milestones are commonly used in international vehicle transactions, although the exact structure varies by supplier. Avoid transferring funds to unrelated personal accounts without a clear contractual explanation.
Shipping arrangements also affect the budget. RoRo shipping is generally suitable for vehicles that can be driven or rolled onto the vessel, while container shipping provides enclosed transport and may suit vehicles requiring additional protection or consolidated cargo arrangements. The selected method should be stated in the shipping agreement, together with responsibility for marine insurance and port handling. Buyers should also confirm the expected shipping schedule rather than treating an indicative transit estimate as a guaranteed arrival date.
Common delays include incomplete export declarations, incorrect VIN details, missing certificates, customs valuation disagreements, vessel schedule changes and destination inspection requirements. Electric vehicles introduce further considerations because battery condition and applicable battery transport documentation may need additional attention. Before release, the buyer should receive the final inspection findings, confirmed shipping documents and a clear record of outstanding charges. A written after-sales process for reporting discrepancies is also useful, particularly when the vehicle has already left China and physical remedies are more difficult to arrange.
FAQ
Q: Is customs duty calculated on the purchase price of a used vehicle?
A: Not necessarily. Many customs authorities use a CIF-based valuation that includes vehicle cost, insurance and freight, with additional adjustments or taxes determined by local regulations.
Q: What documents should a buyer request before shipping a used car from China?
A: Request the inspection report, commercial invoice, certificate of origin where applicable, export documentation and confirmation of export licensing. Buyers should also coordinate destination-specific requirements, including Form M and PAAR for applicable Nigerian imports.